Mortgage Broker vs. Bank in New Jersey: Which Is Better for Your Home Loan?
Choosing between a mortgage broker in NJ and a bank can be one of the most important decisions you make when financing a home.
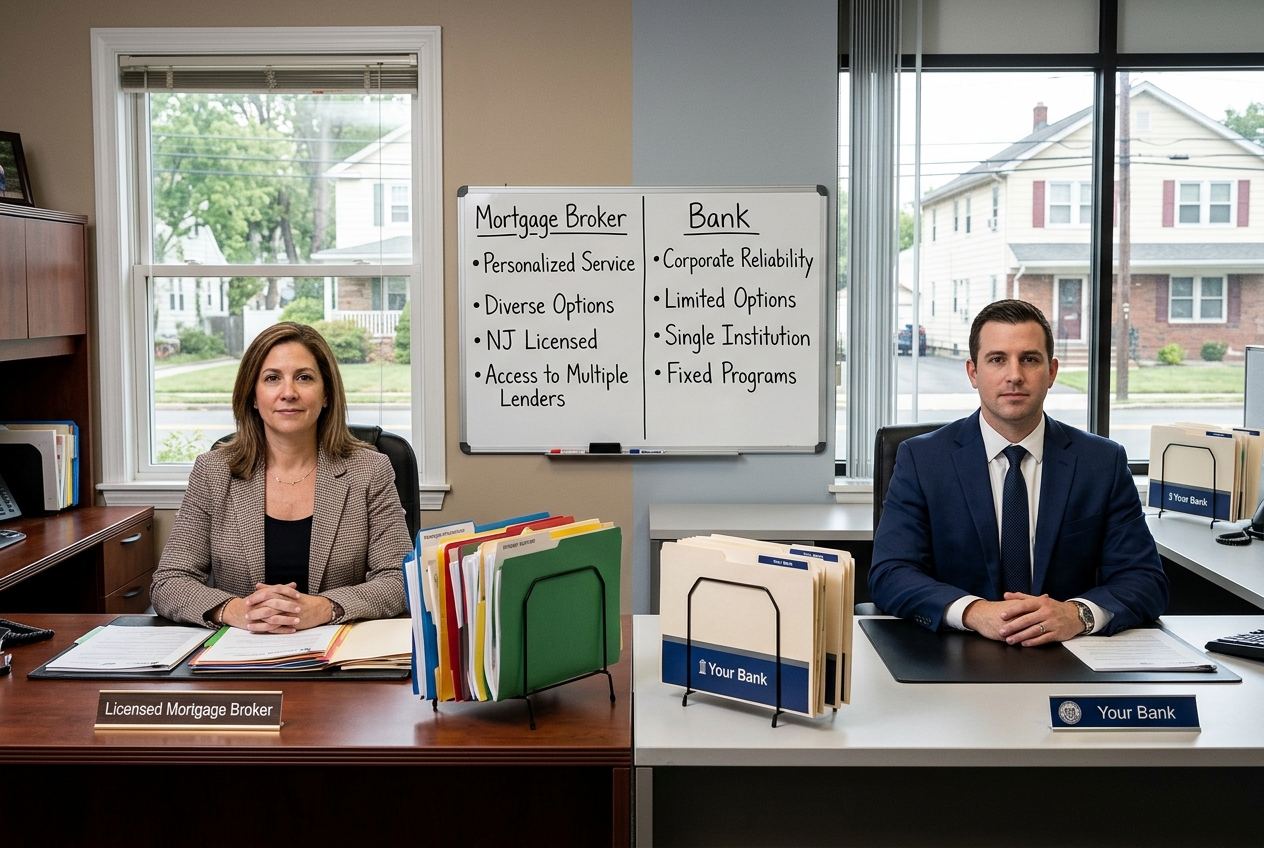
Both can help you obtain a mortgage, but they operate differently. A bank typically offers mortgage products from its own lending platform. A mortgage broker works with multiple lenders and can compare different loan programs for a borrower.
Neither option is automatically better for everyone.
The right choice depends on your credit, income, down payment, property type, loan amount, and how straightforward or complex your financial situation is.
This guide compares a mortgage broker vs. bank in NJ, including rates, fees, loan options, self-employed borrowers, jumbo financing, DSCR loans, the closing process, and situations where either option may make more sense.
What Does a Mortgage Broker Do?
A mortgage broker acts as an intermediary between a borrower and mortgage lenders.
Instead of lending the money directly in the same way a bank does, a broker helps identify mortgage programs from its network of lenders and assists with the application and loan process.
An independent mortgage broker in NJ may have access to multiple lenders offering different:
Interest rates
Loan programs
Underwriting guidelines
Credit requirements
Income-documentation options
Property requirements
Investment-property financing
This can give borrowers more than one potential path to financing.
However, a broker's lender network is not necessarily the entire mortgage market. The number and type of lenders available depend on the brokerage and its relationships.
What Does a Bank Do?
A bank is a financial institution that may offer mortgages directly to consumers.
When you apply through a bank, you are generally working within that institution's mortgage products and underwriting guidelines.
For example, a bank may offer:
Conventional mortgages
FHA loans
VA loans
Jumbo mortgages
Refinancing
Home equity products
The exact products vary between banks.
One potential advantage is that a bank may have an established mortgage operation, existing customer relationship, and streamlined systems for borrowers who fit its standard lending criteria.
What Is a Direct Mortgage Lender?
A direct mortgage lender is another option worth understanding.
A direct lender originates mortgage loans directly rather than acting as an intermediary between the borrower and multiple outside lenders.
Some banks are direct lenders, but not every direct lender is a traditional bank.
The important distinction is simple:
Bank: May offer its own mortgage products and banking relationship.
Direct lender: Provides mortgages directly under its lending platform.
Mortgage broker: Shops available mortgage programs from multiple lenders and helps match the borrower with an appropriate option.
Understanding this difference makes it easier to compare your choices.
Mortgage Broker vs. Bank in New Jersey: The Biggest Difference
The biggest difference is product access.
When you approach one bank, you are generally comparing options within that institution.
When you work with a broker, the broker can potentially compare programs from multiple lenders in its network.
For example, suppose one lender requires a particular income history that you do not have. Another lender may have a program that handles your circumstances differently.
A broker can potentially identify that second option without requiring you to start the entire process from scratch with another institution.
That flexibility can be particularly valuable for borrowers with complex financial profiles.
Is a Mortgage Broker Cheaper Than a Bank?
Not necessarily.
This is one area where borrowers should be cautious about blanket claims.
Mortgage rates and costs vary based on the lender, loan program, credit profile, property, loan amount, market conditions, and other factors.
A mortgage broker may receive compensation from the lender, the borrower, or through a combination structured under applicable rules. The costs should be disclosed clearly as part of the mortgage process.
The Consumer Financial Protection Bureau recommends comparing official Loan Estimates from different lenders. These documents help borrowers compare interest rates, loan terms, closing costs, and other important details.
So instead of asking only, “Who has the lowest rate?”, compare the complete loan offer.
Look at:
Interest rate
Annual percentage rate
Origination charges
Lender credits
Discount points
Closing costs
Prepaid expenses
Monthly payment
Loan terms
The cheapest-looking rate may not produce the lowest overall cost.
Who Has More Mortgage Programs: A Bank or Broker?
This depends on the bank and the broker.
A large bank may offer an extensive range of conventional and government-backed mortgages.
A mortgage broker with a broad lender network may provide access to additional specialty programs that one bank does not offer.
These can include:
Bank statement mortgages
DSCR loans
Non-QM mortgages
Jumbo loans
Investment property financing
Self-employed mortgage programs
Alternative income documentation
For a borrower with a straightforward W-2 profile, the difference may not matter much.
For someone with complex income, it can matter considerably.
Mortgage Brokers and Self-Employed Borrowers
Self-employed borrowers often have a more complicated income profile than traditional W-2 employees.
A business owner may have strong revenue but lower taxable income because of legitimate business expenses and deductions.
That does not automatically make a mortgage impossible, but it can make income qualification more complicated.
A broker may be useful because the borrower can potentially be matched with lenders offering different approaches to self-employed income.
Depending on eligibility, options can include conventional financing, bank statement loans, jumbo financing, and other alternative mortgage programs.
This is one reason borrowers searching for a mortgage broker for self-employed borrowers in NJ may want to compare more than one lending source.
What About DSCR Loans for New Jersey Investors?
Real estate investors have another important consideration.
A DSCR loan evaluates an investment property's rental cash flow rather than relying primarily on the investor's traditional employment income.
A bank may offer investment-property mortgages, but not every bank offers DSCR financing.
A broker with access to lenders specializing in investor financing may be able to compare DSCR programs alongside conventional investment-property loans.
For investors, this can create more flexibility when evaluating:
Rental properties
1–4 unit properties
LLC-owned properties
Portfolio expansion
Cash-out refinancing
Certain short-term rental scenarios
The specific availability and requirements depend on the lender.
What About Jumbo Loans?
Jumbo financing is another area where lender differences can become important.
Jumbo mortgages exceed applicable conforming loan limits and generally have additional underwriting requirements.
Two lenders may evaluate the same high-value borrower differently.
One may have a stronger jumbo program for a particular property or borrower profile, while another may offer more competitive pricing.
A New Jersey mortgage broker with multiple jumbo lending relationships may be able to compare those options instead of limiting the borrower to one institution.
Mortgage Broker vs. Bank: Closing Process
Both banks and brokers can provide a complete mortgage process from application through closing.
The difference is often in who coordinates the various steps.
A broker typically helps manage communication between the borrower and the selected lender.
The process may include:
Initial consultation
Financial and goal review
Loan-program comparison
Application
Document collection
Underwriting
Appraisal
Conditions and final approval
Closing
A bank follows a similar overall path, but the borrower works within that bank's internal mortgage operation.
The speed of either process depends on the lender, loan type, documentation, appraisal, underwriting workload, and transaction complexity.
When Might a Bank Be Better?
A bank may make sense when:
You Have a Simple Financial Profile
A borrower with stable W-2 income, strong credit, and a conventional purchase may find a bank's process straightforward.
You Already Have a Strong Banking Relationship
Some borrowers prefer keeping their mortgage and other financial services with the same institution.
The Bank Offers a Competitive Product
If the bank provides the right mortgage at an attractive overall cost, there may be little reason to look elsewhere.
You Prefer One Institution
Some borrowers value having one point of contact and a familiar financial institution.
There is nothing inherently wrong with choosing a bank when it fits your needs.
When Might a Mortgage Broker Be Better?
A broker may be worth considering when:
You Want to Compare Multiple Lenders
A broker can potentially shop your scenario across its lender network.
Your Income Is Complicated
Self-employed, 1099, commission, business, rental, and investment income can require more careful analysis.
You Need a Specialty Loan
Bank statement, DSCR, non-QM, jumbo, or other specialized programs may not be available from every bank.
Your Situation Does Not Fit a Standard Lending Box
Multiple properties, unusual income structures, or investment strategies can make lender selection more important.
You Want Someone to Help Compare Options
An experienced broker can help explain the differences between programs and present options that fit your circumstances.
Bank vs. Mortgage Broker: A Quick Comparison
Factor | Bank | Mortgage Broker |
|---|---|---|
Lender access | Primarily its own products | Multiple lenders in network |
Rate options | Based on bank's pricing | Can compare participating lenders |
Loan programs | Depends on bank | Depends on lender network |
Self-employed financing | Available on qualifying programs | Can compare multiple approaches |
DSCR financing | Not offered by every bank | May have access through specialty lenders |
Jumbo loans | Often available | Can compare multiple jumbo lenders |
Personal banking relationship | Often available | Usually separate |
Shopping multiple lenders | You do it yourself | Broker can shop its network |
Fees | Vary | Vary |
Best for | Borrowers who fit the bank's products | Borrowers who value lender comparison |
What Should You Ask Before Choosing a Mortgage Provider?
Whether you choose a bank, direct lender, or broker, ask questions before committing.
Consider asking:
How many lenders can you access?
Which loan programs fit my situation?
What are the total estimated closing costs?
How is compensation structured?
Can I compare multiple Loan Estimates?
How do you handle self-employed income?
Do you offer investment-property financing?
Do you offer DSCR loans?
What happens if the first loan option does not work?
Who will manage the process through closing?
The goal is to understand exactly what you are getting.
How Virtue Funding Approaches Mortgage Financing
Virtue Funding LLC is an independent mortgage brokerage based in Hawthorne, New Jersey.
Rather than offering only one institution's mortgage menu, Virtue Funding works with a network of lenders and compares available programs based on the borrower's situation.
Its mortgage options include conventional, FHA, VA, USDA, jumbo, bank statement, DSCR, refinance, HELOC, and other financing solutions.
That approach can be particularly useful for borrowers who do not fit neatly into a standard mortgage profile, including self-employed borrowers, business owners, investors, and borrowers seeking specialty financing.
Virtue Funding is licensed in New Jersey, Pennsylvania, South Carolina, and Florida.
So, Is a Mortgage Broker or Bank Better in New Jersey?
There is no universal winner in the bank vs. mortgage broker comparison.
A bank may be the right choice when its mortgage program fits your financial profile, pricing is competitive, and you value an existing banking relationship.
A mortgage broker may be a better fit when you want to compare multiple lenders or have a more complicated income or property situation.
The most important question is not simply “Should I use a broker or a bank?”
It is:
“Which financing option best fits my financial situation and home-buying goals?”
Comparing the total cost, loan terms, qualification requirements, and available programs can help you make a more informed decision.
Final Thoughts
Choosing a mortgage broker in NJ does not guarantee a lower rate or easier approval. Choosing a bank does not guarantee the best mortgage either.
The right provider depends on your individual circumstances.
For a straightforward W-2 borrower, a bank may provide exactly what is needed. For a self-employed borrower, investor, jumbo buyer, or someone seeking alternative financing, access to multiple lenders may provide additional options worth comparing.
If you want to see which approach makes sense for your situation, speak with a Virtue Funding mortgage advisor about your specific situation. Virtue Funding can review your goals and financial profile, compare available mortgage programs, and help you understand your options without forcing you into a single bank's product menu.
All mortgage applications are subject to credit approval, verification of income and assets, satisfactory appraisal, and applicable underwriting guidelines. Rates, terms, programs, and eligibility requirements are subject to change without notice. Virtue Funding LLC arranges loans with third-party providers and does not make mortgage loan commitments or fund mortgage loans.